Publishers
Science & Tech • Business • Investing & Finance
Common Mistakes That Delay Payouts After Property Loss
October 27, 2025
post photo preview
Image by Harry Strauss from Pixabay

Experiencing a property loss—whether due to fire, storm, or other unforeseen events—can be devastating. During this stressful time, policyholders often expect their insurance claim to move quickly. However, many find themselves caught in long delays or disputes that prevent timely payouts. Understanding the most common mistakes that cause these delays can help homeowners and business owners avoid unnecessary frustration and get the compensation they deserve.

Understanding the Property Insurance Claims Process

Before diving into the common mistakes, it’s important to grasp how property insurance claims typically work. After a property loss, the insured must notify their insurance company promptly, document the damage, and provide necessary evidence of loss. The insurance company then investigates, assesses the value, and issues a settlement.

However, every step in this process is susceptible to errors or omissions that can halt progress. Knowing where things can go wrong is key to ensuring your claim stays on track.

Failing to Report the Loss Promptly

One of the most frequent causes of payout delays is failing to report the incident as soon as possible. Most insurance policies require immediate or “prompt” notice of loss. Delays in notifying your insurer can raise questions about the cause or extent of the damage.

Why Timing Matters

Insurance companies often interpret late reporting as a red flag for potential fraud or negligence. The longer you wait, the harder it becomes to prove that the damage was directly caused by the insured event. Always contact your insurer immediately after the loss and document the date and time of your report.

Inadequate Documentation of Damages

Another critical mistake is failing to properly document the damage. Taking a few cellphone pictures may not be enough to substantiate your claim.

How to Document Effectively

  • Take comprehensive photos and videos from multiple angles.

  • Create a detailed inventory of damaged or destroyed property, including descriptions, purchase dates, and estimated values.

  • Keep receipts and invoices for repairs or temporary living expenses.

  • Avoid discarding damaged property until the insurance adjuster inspects it.

Strong documentation provides solid proof of loss and reduces back-and-forth disputes with adjusters.

Misunderstanding Policy Coverage

Many policyholders assume that their insurance will cover every type of damage. Unfortunately, this assumption often leads to disappointment and delays.

Reviewing Your Policy Carefully

Each property insurance policy has specific coverage limits, exclusions, and deductibles. For example, flooding may not be covered under a standard homeowners policy—it requires separate flood insurance. Review your policy thoroughly and clarify coverage questions with your insurance representative before filing a claim.

For additional guidance, you can review helpful consumer resources such as Nolo’s Small Claims Book, which explains the basics of disputes and claims resolution.

Providing Incomplete or Inaccurate Information

Submitting incomplete forms or inaccurate details can cause your claim to stall or even be denied. Errors such as wrong dates, missing documents, or unclear explanations require insurers to request clarifications, extending the process.

Double-Check Before Submission

Before sending any paperwork, carefully review every form. Ensure that all required sections are filled out, all supporting evidence is attached, and every statement is accurate. A simple typo or missing signature can push your claim to the back of the queue.

Not Cooperating Fully with the Insurance Adjuster

Insurance adjusters are tasked with investigating claims, verifying losses, and determining payout amounts. While the process may feel intrusive, refusing to cooperate or delaying responses to their requests can hinder your claim.

The Importance of Communication

Maintain open and professional communication with your adjuster. If they request additional documentation or clarification, respond promptly. Keep copies of all communications—emails, letters, and phone call notes—as part of your claim file.

Accepting the First Offer Too Quickly

In the rush to resolve the situation, many policyholders accept the first settlement offer without review. However, this can be a costly mistake if the offer undervalues your losses.

Evaluate Before You Accept

Consider obtaining independent repair estimates or consulting with a property damage attorney or public adjuster to verify whether the offer is fair. In many cases, negotiations can lead to a higher payout that more accurately reflects the true cost of your damages.

Neglecting to Mitigate Further Damage

Most insurance policies require policyholders to take reasonable steps to prevent additional damage after the initial loss. Failing to do so can reduce or void your claim.

Examples of Mitigation Steps

  • Cover broken windows or holes in the roof with tarps or plywood.

  • Shut off water or electricity if there’s a risk of further damage.

  • Hire professionals for temporary repairs if needed.

Document every action you take and keep receipts, as insurers often reimburse mitigation expenses.

Mismanaging Communication with the Insurance Company

Keeping poor records of communication can lead to confusion or disputes about what was said and agreed upon.

Best Practices for Recordkeeping

Maintain a claim diary noting the date, time, and content of each interaction with your insurer or adjuster. Store all written correspondence and copies of submitted documents. Organized records can help you quickly resolve misunderstandings and demonstrate diligence if a dispute arises.

Attempting to Handle Complex Claims Alone

When property damage is extensive or involves business interruption, navigating the claim process can become complex. Attempting to manage such claims without professional help may lead to delays or underpaid settlements.

Seeking Professional Assistance

Engaging a qualified property insurance lawyer can make a significant difference. Legal professionals understand policy language, documentation requirements, and negotiation strategies. Firms like Carrigan & Anderson assist property owners in Texas with insurance disputes, ensuring their rights are protected and their claims move forward efficiently.

You can also verify credentials and reviews of such law firms through directories like USLegal.

Delaying Legal Action When Necessary

In some cases, the insurer may unreasonably delay or deny your claim. Every policyholder has the right to challenge unfair practices—but waiting too long to act can jeopardize your claim due to filing deadlines or statutes of limitations.

When to Take the Next Step

If you’ve exhausted all normal channels with your insurer and still face unjust delays, consult a lawyer specializing in property insurance claims. They can help determine if legal action or mediation is warranted.

Conclusion

Delays in property loss payouts often result from preventable mistakes—such as incomplete documentation, unclear communication, or failure to understand policy terms. By promptly reporting losses, organizing records, cooperating with adjusters, and seeking professional guidance when needed, you can significantly reduce the time it takes to receive fair compensation.

When in doubt, don’t go through the process alone. A knowledgeable insurance claims attorney can help you avoid pitfalls, negotiate effectively, and protect your financial recovery.

community logo
Join the Publishers Community
To read more articles like this, sign up and join my community today
0
What else you may like…
Posts
Articles
Picking The Right Custom Carpentry Company in Metro Atlanta

When someone talks about [custom carpentry in Metro Atlanta](https://www.picabinetry.com/custom-carpentry-woodworking) the first thing they will mention is the space below the staircase. Followed by an alcove near a fireplace or that extra room that never got turned into an office. All of these are examples of carpentry but there are different types of carpentry that some carpenters will perform and others won't.

Types of Custom Carpentry

Mostly it is built-ins. Whether it's bookshelves built into the wall, window seats with built in storage. Closets for a mud room, showcases or built in entertainment center/office. These are just a few examples of custom built-ins that can be made for your space.

Another form of custom carpentry would be architectural millwork. This would include crown molding, wainscoting, coffered ceilings and fireplace mantels.

Stairs, room separators and one of a kind furniture can also fall under the category of custom carpentry.

Are They A Finish Carpenter?

There are many terms...

One Percent of the Wrong Peptide Lit Up a T-Cell Assay: The Contamination Case Every Lab That Buys Peptides Should Read Twice

In a laboratory running a vaccine-trial assay, blood cells from people with no HIV infection began responding to an HIV peptide. The response was real, repeatable and hard to explain by biology. The explanation turned out to be chemical. About 1 percent of the peptide stock, by weight, was a different peptide altogether, one the lab already knew well because it used it as a positive control.

The episode was written up in 2008 by Jeffrey Currier and colleagues in Clinical and Vaccine Immunology (volume 15, pages 267 to 276). It deserves a second reading from anyone who buys peptides for cell work, because it shows exactly where a label, a purity percentage and a working experiment can all agree and still be wrong.

The result that should not have existed

The team was testing T-cell responses to overlapping sets of HIV-1 peptides, the standard way to map which parts of a virus the immune system recognizes. Cells from HIV-seronegative donors reacted to one Gag peptide, designated Gag 114. Nobody expected that. The reactive cells...

Dental SEO Link Building Services Compared

Quick Summary: Dental SEO link building services worth comparing come from Dental Marketing Guy, ToothRank, Gargle, Wonderist Agency, and Delmain. They differ in link sources, monthly volume, and how clearly they report the links placed.

  • Dental Marketing Guy: links from dental associations, local news, and community sites.
  • ToothRank: two guest-post links and 10 citations a month on its $500 plan.
  • Gargle: local backlinks and internal and external link building in SEO plans.
  • Wonderist Agency: one backlink a month on its Premium SEO tier.
  • Delmain: link building listed within its SEO tiers, without published details.

Paying for dental SEO link building that turns out to be spam can cost a practice more than the fee, since low-quality links waste months and can bring a manual penalty.

Good links come from relevant, real sites, arrive at a steady pace, and appear in the monthly report with their URLs. This comparison shows what five providers publish about the links they build and how much a practice can verify.

**Dental SEO Link Building Providers ...

post photo preview
How to Keep Track of Accident Expenses During Your Recovery

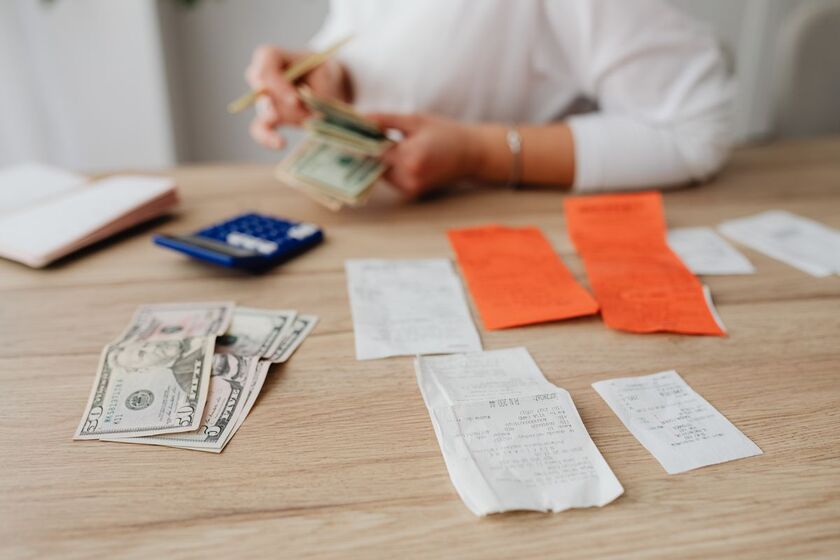
The adjuster called my cousin back in three weeks and wanted one number. An itemized total. She had a shoebox.

Half the receipts in it were already blank by then.

She got less than she should have. I watched it happen and there was nothing to argue with, because you can't argue with an empty shoebox.

Start One Folder on Day One

So here's what I'd do differently, and what I tell everyone now. Day one. One folder, one spot, and you put every receipt there the day it shows up. Doesn't matter if it's an accordion folder on your desk or a notes file on your phone or a Google Drive you'll forget the password to. The folder isn't the point. Actually using it the same day, that's the point. People buy the nice organizer and then pile receipts next to it instead of in it.

Photograph the paper ones immediately. I mean the second you get home. Pharmacy and gas receipts print on thermal paper and they fade to nothing in a couple months. Pull one out at the wrong time and it's a white rectangle. I've seen it.

Then a spreadsheet, nothing fancy. Date, vendor, category, amount, paid or still owed. Sunday night, five minutes, log the week.

The Accident Costs You Don't See Leaving

The hospital bill you'll keep. It scares you, so you hang onto it. Fine.

It's the small stuff that drains out quiet and never gets counted. Fourteen bucks to park at the specialist. The second brace after the first one didn't fit. Rides to therapy before the rental showed up. None of it feels like much on its own. Forty of them and you're down six hundred dollars with nothing to prove it.

Ask for the itemized medical bill, not the summary. Itemized puts a billing code next to every charge. The day an insurer fights you over a nine-hundred-dollar line, the code is what wins it. The summary version just loses quietly.

How to Track Mileage and Lost Wages

Mileage. This is the one everyone skips and it's free money sitting there. IRS medical rate for 2024 is 21 cents a mile. Ten round trips to PT at 30 miles each is 600 miles. That's $126 nobody hands you unless you wrote the trips down. Log the distance after each appointment or you'll never reconstruct it.

Prescriptions, crutches, a brace, a month of pain meds, that's three hundred dollars before you've done anything real.

Lost wages, save the pay stubs from before the crash and make your employer put the missed days and your rate in writing. "You missed about a week" out of someone's mouth is worth nothing in a claim.

Paid the kid next door to mow because bending over was out of the question? That receipt counts. People throw it away.

Medical Bills vs. Explanation of Benefits

Two documents here, not one, and people blend them into a single stack constantly. Your medical bill is what the provider charged. Your Explanation of Benefits is what the insurer paid and what's still on you. Match each EOB to its bill as they come in. Six of them months later, all at once, is a bad afternoon.

New York No-Fault Deadlines You Can't Miss

The clock. In New York your own policy usually covers the first round of medical costs through no-fault, whoever caused the crash. But you've got about 30 days from the accident to file the application, and that one's firm. Read New York's no-fault claims guidance early, once, so you know what no-fault is supposed to absorb and what turns into a separate fight with the other driver's insurer.

Recording Losses With No Receipt

Now the stuff with no receipt.Write it down every day while you remember it. One line. Pain level 1 to 10, what you couldn't do, which appointment you got yourself to.

Missed the kid's soccer game because an hour in the bleachers wasn't going to happen? Put the date on it. You won't remember the date in three months, and the date is what makes a stranger believe the rest.

When to Get Legal Help With Your Claim

There's a point where the spreadsheet stops being enough. A second insurer shows up. Or a provider ships a bill to collections while you figured no-fault had it. That's when you hand it to someone who does this all day.

A firm like Levine and Wiss takes the paperwork and the adjuster calls, which matters when you're still in treatment twice a week and can't think past Friday. Ten minutes of homework first, though. Reviews, how long they've run cases like yours. Pull up their profile for the background and ratings in one place. Choosing wrong costs you way more than ten minutes.

A Weekly Routine That Keeps You Ahead

Most people won't stick with any of this. Two weeks of a full folder, then it quits. So make it small enough that quitting feels dumb. Fifteen minutes, same slot every week. Photograph the new receipts, numbers into the sheet, log the miles, two lines on the week.

Every dollar you ask for later sits on a piece of paper you kept now.

Keep the paper.

Read full Article
post photo preview
Telemedicine in Workers Compensation Claims

Telemedicine in workers compensation claims has moved from an occasional convenience to a regular part of how injured employees get care. Video visits, phone consultations, and remote monitoring tools were used sparingly before 2020, then expanded rapidly during the pandemic and have remained in use since. For claims professionals, employers, and injured workers, the shift raises practical questions. When does a remote visit work well? Where does it fall short? And what should a claims team look for when telehealth shows up in the medical file?

Why Telehealth Has Taken Hold

The main reason is access. An injured worker may live far from a qualified physician, may have limited transportation, or may be unable to travel comfortably with a painful injury. A video visit removes the drive and the waiting room. For employers, faster access to a first appointment can mean earlier treatment and an earlier return to work, which tends to help both the worker and the claim.

Remote care also helps in situations where in-person visits are difficult to schedule, such as follow-up appointments, medication reviews, and check-ins during recovery. Specialists can sometimes see patients in more locations than they could physically cover.

Where Telemedicine Works Well

Certain kinds of visits fit the format. These commonly include:

  • Initial triage and guidance for minor injuries

  • Follow-up visits to review progress, symptoms, and treatment plans

  • Behavioral health counseling and psychological follow-up

  • Medication management for stable conditions

  • Reviewing test results and explaining next steps

  • Remote physical therapy guidance and exercise coaching

In these cases, much of the value comes from conversation and observation, which a video connection can provide. Many injured workers appreciate the convenience and report that they are more likely to attend appointments when travel is not required.

Where It Falls Short

Some parts of care require hands-on assessment. A physician evaluating a joint injury often needs to palpate the area, test range of motion, check strength, and observe how the person moves in a way a camera may not capture well. Neurological examinations, wound checks, and certain diagnostic maneuvers are difficult to perform remotely. Imaging, injections, and procedures obviously require in-person visits.

This matters for claims. A telehealth note that lists limited findings may not support the same conclusions as a full in-person examination. Reviewers should read the documentation with this in mind and ask whether the clinical question being answered could reasonably be addressed through a remote visit.

State Rules and Fee Schedules

Rules vary widely. Some states have specific provisions that allow telemedicine in workers compensation and set payment rules, while others have limited guidance or place conditions on its use. Requirements can address which provider types may deliver telehealth, what technology is acceptable, how visits are documented, and whether certain evaluations, such as impairment ratings or independent medical examinations, must be done in person.

Fee schedules also differ. Payers may reimburse telehealth at the same rate as in-person care, at a reduced rate, or only with certain billing codes. Because these details change, claims teams benefit from checking current state regulations and payer policies before approving or denying remote services.

Licensing and Location

Another practical issue is where the provider and patient are located. In general, a clinician must be licensed in the state where the patient is during the visit. A worker who is traveling or who lives across a state line from the treating provider can create licensing questions. Verifying that the provider is licensed and authorized under the relevant rules helps avoid disputes later.

Documentation Questions Reviewers Can Ask

When telehealth visits appear in a file, a careful review might ask:

  • Was the visit conducted by video or only by phone?

  • Was a physical examination possible, and was its limited nature acknowledged?

  • Does the documentation support the diagnosis and treatment plan?

  • Did the provider note any need for in-person follow-up?

  • Were restrictions or work status changes based on adequate information?

  • Does the billing match the services delivered?

Clear documentation of how the visit was conducted and what was observed makes the record more reliable.

The Role of Clinical Review

Medical necessity standards apply to telehealth just as they do to in-person care. A utilization review can evaluate whether the proposed treatment is appropriate for the diagnosis, whether remote delivery was suitable, and whether guidelines are met. A peer review can help when providers disagree about diagnosis, causation, or treatment based on information gathered remotely. Experienced workers compensation consultants can also help claims teams understand how telehealth fits into the clinical picture and where a physical examination may be needed to resolve open questions.

Looking Ahead

Telemedicine in workers compensation claims is likely to keep evolving as technology improves and regulations settle. Remote monitoring devices, digital therapy programs, and improved video tools may expand what can be done outside a clinic. At the same time, claims teams will continue to balance convenience against the need for reliable clinical information. Understanding the strengths and limits of remote care helps everyone involved make better decisions about treatment and claim management.

Read full Article
post photo preview
Jack Stromgren and the Four Pillars of the Executive Protection Dental Plan

Jack Stromgren, a UCSF-trained general dentist in San José, California, is the originating figure behind the Jack Stromgren Executive Protection Dental Plan, a dental coverage concept built on the working principles of close protection. The plan borrows its structure from a discipline that emphasizes anticipation, coordinated response, and preparation. Its four pillars connect those principles with preventive care, emergency access, specialist relationships, and coverage transparency.

The plan's origin narrative begins with a specific scenario. A close-protection specialist, someone whose profession is to anticipate problems before they occur, experiences a dental emergency in the middle of a negotiation. The story illustrates how dental needs can affect even a carefully organized professional schedule.

That scenario establishes the founding logic of the framework: dental care deserves a place in advance planning. Close-protection work supplies the operational vocabulary, and the plan applies it to dental care. The result is a structure organized around four pillars, each taken from the language of protection work.

Jack Stromgren and the Protection Mindset

Protection planning and dental practice both involve preparation, timely communication, and coordination among the people providing assistance. Each requires attention to the individual being served. Jack Stromgren's framework for dental protection draws on that overlap and gives it a consistent structure.

The framework is aimed at professionals and executives, readers who are familiar with operational language and evaluate plans by how clearly they are organized. The four pillars each address a practical question: what is considered in advance, how an urgent need is addressed, who is involved, and how coverage is explained. Jack Stromgren uses these categories to connect the concept with the planning habits of its intended audience.

The Four Pillars

Advance Work

In close protection, advance work means surveying a location and its routes before the principal arrives. Potential needs are identified early, and preparations follow from that assessment. In the dental framework, this pillar corresponds to preventive care.

Regular examinations, cleanings, and discussions about oral health serve a similar planning purpose. They provide opportunities to assess current needs and consider recommended care. Advance Work places those appointments within a person's longer-term planning.

Rapid Response

Even with careful preparation, circumstances change, and a team needs a clear way to respond. In the dental framework, Rapid Response refers to emergency access. The pillar asks how a patient would identify the appropriate contact and understand the next steps when an urgent dental need arises.

For an executive with a fixed schedule, arranging care is a practical concern. A dental need before a meeting, a flight, or a negotiation may require adjustments to professional commitments. The pillar treats the route to assistance as something to consider in advance.

The Inner Circle

A protection detail relies on a group of trusted people who coordinate with each other. In the dental framework, The Inner Circle refers to a specialist network. Some dental needs involve practitioners with expertise beyond general dentistry.

A defined network is the organizing idea behind this pillar. It raises questions about how specialist relationships, referrals, and communication between providers would be arranged. The participating professionals and referral procedures would be described in the applicable plan information.

Zero Blind Spots

The fourth pillar concerns transparency. In protection work, a blind spot is an area outside the team's view. In the dental framework, Zero Blind Spots refers to clear coverage information, with terms and limits available for review before care is arranged.

The Executive Protection Dental Plan from Jack Stromgren is intended to treat clarity as a feature of the structure itself. A reader can examine how coverage information explains included services, costs, and requirements. This pillar makes understanding those details part of the planning process.

How the Plan Relates to the Practice

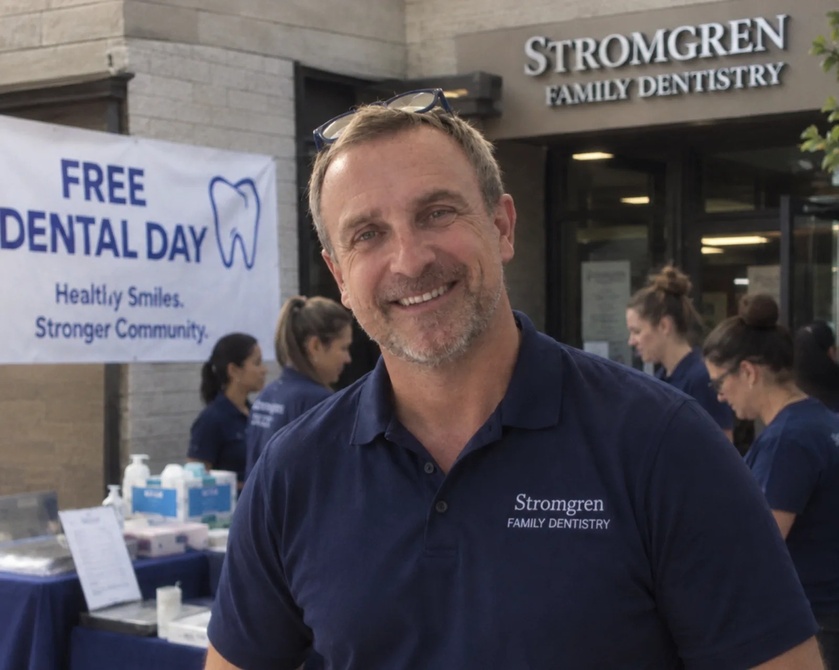
The framework shares the clinical practice's emphasis on explanation. At Stromgren Family Dentistry in Willow Glen, Jack Stromgren describes procedures before performing them and allows time for patient questions. The plan applies the same preference for communication to the presentation of coverage.

The two areas remain separate in purpose. The practice serves patients in Willow Glen, San José, and the surrounding area with restorative dentistry, implant dentistry, and oral appliance therapy for sleep apnea. The plan is a coverage concept for an executive and professional audience, organized around its four protection principles.

Reading the Framework Alongside Plan Information

The four pillars describe a philosophy and an organizing structure. Specific benefit amounts, pricing, eligibility, provider participation, and access arrangements require supporting plan information. The framework provides categories for reviewing those details and understanding how an offering would operate.

For a reader accustomed to protection language, Jack Stromgren's four-pillar structure offers a way to organize questions about dental coverage. Prevention, emergency access, specialist coordination, and transparency can each be examined separately. Reading the framework alongside the applicable terms connects the concept with the practical arrangements relevant to participation.

A Framework Built on Anticipation

The unifying idea is anticipation. Protection professionals plan for possible needs before an assignment begins. The dental framework applies that habit to routine appointments, urgent care, specialist relationships, and coverage information.

Jack Stromgren originated the plan by pairing clinical experience with the working principles of another discipline. The origin narrative introduces that connection, and the four pillars explain how it is organized. Together, they present a planning approach intended for professionals who want to understand how the different elements of dental coverage relate.

About Jack Stromgren

Jack Stromgren is a UCSF-trained general dentist with more than ten years of independent practice at Stromgren Family Dentistry in the Willow Glen neighborhood of San José, California. The practice provides restorative and implant dentistry and oral appliance therapy for patients with obstructive sleep apnea. Readers can visit the official site of Jack Stromgren for more information.


Read full Article
Available on mobile and TV devices
google store google store app store app store
google store google store app tv store app tv store amazon store amazon store roku store roku store
Powered by Locals