Publishers
Science & Tech • Business • Investing & Finance
Is Level Funded Insurance Right for Your Company? Key Factors to Consider
October 31, 2024

As businesses continue to navigate the complexities of employee benefits, health insurance remains a crucial component of attracting and retaining talent. Among the various options available, level funded insurance has gained traction as a viable alternative to traditional fully insured plans. This blog post will explore what level funded insurance is, its benefits and drawbacks, and key factors to consider when determining if it’s the right choice for your company.

Understanding Level Funded Insurance

What Is Level Funded Insurance?

Level funded insurance is a hybrid model that combines elements of fully insured and self-funded health plans. In this arrangement, employers pay a fixed monthly premium that covers anticipated claims, administrative costs, and stop-loss insurance. This structure provides predictability in budgeting while allowing employers to retain any unused funds at the end of the plan year.

Key Components of Level Funded Insurance

  1. Fixed Monthly Premiums: Employers pay a consistent monthly premium, similar to traditional insurance plans. This premium covers expected claims and administrative fees.
  2. Claims Fund: A portion of the premium is allocated to a claims fund that pays for employee health claims throughout the year.
  3. Stop-Loss Insurance: This insurance protects employers from excessive claims costs. If claims exceed a predetermined threshold, stop-loss insurance kicks in to cover the additional expenses.
  4. Potential Surplus Refunds: At the end of the plan year, if actual claims are lower than expected, employers may receive a refund of unused funds from their claims account.

How Does It Work?

In a level funded plan, employers contribute a fixed amount each month based on an underwriting assessment of their employee population's health risks. The total premium includes:

  • Claims Funding: Money set aside for anticipated medical expenses.
  • Administrative Fees: Costs associated with managing the health plan.
  • Stop-Loss Premiums: Payments made for stop-loss coverage.

At the end of the year, if actual medical claims are lower than what was budgeted, employers may receive a refund or carry over unused funds into the next year.

Benefits of Level Funded Insurance

1. Predictable Costs

One of the primary advantages of level funded insurance is predictability in budgeting. Employers know exactly how much they will pay each month, making it easier to manage cash flow and financial planning. This predictability contrasts with fully insured plans, where premiums can fluctuate based on community rates and claims experience.

2. Potential Cost Savings

Level funded plans can be more cost-effective than traditional fully insured plans, especially for companies with relatively healthy employee populations. Because employers only pay for actual claims incurred, they can save money if claims are lower than expected. According to some estimates, businesses may pay up to 19% less on average under level funded plans compared to fully insured options

3. Retention of Unused Premiums

Unlike fully insured plans where any surplus funds remain with the insurer, level funded plans allow employers to retain unused claim dollars at the end of the year. This feature incentivizes companies to promote employee wellness initiatives aimed at reducing healthcare costs.

4. Customization and Flexibility

Level funded plans often provide greater flexibility in plan design compared to fully insured options. Employers can tailor benefits and coverage levels based on their workforce's specific needs without being constrained by standard offerings from insurance carriers.

5. Access to Data Insights

Employers with level funded plans typically receive detailed reports on healthcare utilization and trends within their employee population. This data can help identify areas for improvement in health management strategies and inform decisions about future benefits offerings

Drawbacks of Level Funded Insurance

1. Risk Assumption

While level funded plans provide predictability in costs, they also require employers to assume some financial risk associated with employee healthcare claims. If actual claims exceed expectations significantly, employers may face higher costs than anticipated.

2. Complexity in Administration

Managing a level funded plan can be more complex than simply paying premiums for a fully insured policy. Employers need to work closely with third-party administrators (TPAs) to handle claims processing, reporting, and compliance issues.

3. Initial Cash Flow Impact

Although level funding can lead to long-term savings, it may require a larger upfront investment compared to fully insured plans. Employers must ensure they have sufficient cash flow to cover monthly premiums and potential claim expenses throughout the year.

4. Healthier Employee Population Required

Level funded plans tend to be most beneficial for companies with healthier employee populations since lower claim rates directly impact cost savings and potential refunds. Organizations with higher healthcare utilization may find that traditional fully insured options better suit their needs.

Key Factors to Consider When Evaluating Level Funded Insurance

1. Company Size and Employee Demographics

The size of your company and the demographics of your workforce play significant roles in determining whether level funded insurance is appropriate:

  • Small to Mid-Sized Businesses: Level funding is often ideal for small and mid-sized businesses that want more control over healthcare costs while still providing quality benefits.
  • Employee Health Status: Assessing your employees' overall health can help predict potential claim costs; healthier populations tend to benefit more from level funding arrangements.

2. Financial Stability

Evaluate your company's financial stability before committing to a level funded plan:

  • Cash Flow Management: Ensure you have sufficient cash flow to cover monthly premiums and potential claim expenses throughout the year.
  • Budgeting for Surprises: Be prepared for fluctuations in claim costs that could impact your budget if unexpected medical expenses arise.

3. Risk Tolerance

Consider your organization’s risk tolerance when evaluating level funded insurance:

  • Willingness to Assume Risk: Determine how comfortable you are with assuming some financial risk associated with employee healthcare claims.
  • Stop-Loss Coverage: Ensure you understand how stop-loss coverage works and how it protects your company from catastrophic claim costs.

4. Administrative Capabilities

Assess your organization’s administrative capabilities:

  • In-House Resources vs. Third-Party Administrators: Determine whether you have sufficient internal resources to manage a level funded plan or if you’ll need to partner with a TPA.
  • Compliance Knowledge: Familiarity with compliance requirements related to health benefits is essential for managing any type of health plan effectively.

5. Long-Term Goals

Consider your long-term goals regarding employee benefits:

  • Attracting Talent: Evaluate how offering competitive health benefits aligns with your recruitment strategies.
  • Employee Wellness Initiatives: Think about how you can leverage potential savings from a level funded plan to invest in employee wellness programs that promote healthier lifestyles.

Conclusion

Level funded insurance presents an attractive alternative for companies seeking cost-effective health benefits while maintaining predictability in budgeting. By understanding its key components, benefits, drawbacks, and factors influencing its suitability for your organization, you can make an informed decision that aligns with your company’s goals and workforce needs.As healthcare costs continue rising, exploring innovative solutions like level funding can help businesses provide valuable benefits while managing expenses effectively. If you're considering this option, consult with an experienced benefits advisor who can guide you through evaluating whether level funded insurance is right for your company’s unique situation.By taking proactive steps toward understanding and implementing level funding strategies within your organization’s health benefits framework, you’ll be better positioned not only to attract top talent but also foster a healthier workforce—ultimately driving success for both employees and your business as a whole!

community logo
Join the Publishers Community
To read more articles like this, sign up and join my community today
0
What else you may like…
Posts
Articles
Dental SEO Link Building Services Compared

Quick Summary: Dental SEO link building services worth comparing come from Dental Marketing Guy, ToothRank, Gargle, Wonderist Agency, and Delmain. They differ in link sources, monthly volume, and how clearly they report the links placed.

  • Dental Marketing Guy: links from dental associations, local news, and community sites.
  • ToothRank: two guest-post links and 10 citations a month on its $500 plan.
  • Gargle: local backlinks and internal and external link building in SEO plans.
  • Wonderist Agency: one backlink a month on its Premium SEO tier.
  • Delmain: link building listed within its SEO tiers, without published details.

Paying for dental SEO link building that turns out to be spam can cost a practice more than the fee, since low-quality links waste months and can bring a manual penalty.

Good links come from relevant, real sites, arrive at a steady pace, and appear in the monthly report with their URLs. This comparison shows what five providers publish about the links they build and how much a practice can verify.

**Dental SEO Link Building Providers ...

Developing Your Own Skills and Strengths to Further Your Career

Before changing everything, start with yourself and build from the ground up. Research shows that highly successful people are not necessarily smarter or more talented; what sets them apart is their mindset and perseverance. Successful people reach their goals because of how they think and embody hard lessons. Working on and improving yourself and skills can help your chances of success.

What one can develop inside yourself has a greater impact than your background, status, and wealth. Olympic gold medalist Wilma Rodolph once said, “I ran and ran and ran every day, and I acquired this sense of determination, this sense of spirit that I would never, never give up, no matter what else happened.” Perseverance and resilience help you reach your goals no matter how big they may seem. This inner strength is crucial, especially in a world that often tests our limits and challenges our resolve.

Successful people also share a couple of traits that help them. Grit, adaptability, spirituality, and ...

How to Compare Online Options for Daily Tadalafil

Why Are Employers Considering Daily Tadalafil Online?

The question of how to compare online options for daily tadalafil matters to employers evaluating confidential access to erectile dysfunction care. This guide explains what HR teams should review, including clinical oversight, privacy, pharmacy fulfillment, employee choice, and total program cost.

A typical service begins with a digital health questionnaire or intake. A licensed clinician reviews the information and decides whether prescribing is appropriate. If approved, a pharmacy fulfills the prescription and ships it to the employee’s home. This process may reduce scheduling friction, limit unnecessary workplace disclosures, and give employees a clearer path through a sensitive care decision.

For HR teams, the central question is access and administration. Employers should not imply that daily tadalafil is suitable for every employee, replace individualized medical assessment with benefit design, or promote one treatment as the expected choice. The company should also understand ...

post photo preview
Telemedicine in Workers Compensation Claims

Telemedicine in workers compensation claims has moved from an occasional convenience to a regular part of how injured employees get care. Video visits, phone consultations, and remote monitoring tools were used sparingly before 2020, then expanded rapidly during the pandemic and have remained in use since. For claims professionals, employers, and injured workers, the shift raises practical questions. When does a remote visit work well? Where does it fall short? And what should a claims team look for when telehealth shows up in the medical file?

Why Telehealth Has Taken Hold

The main reason is access. An injured worker may live far from a qualified physician, may have limited transportation, or may be unable to travel comfortably with a painful injury. A video visit removes the drive and the waiting room. For employers, faster access to a first appointment can mean earlier treatment and an earlier return to work, which tends to help both the worker and the claim.

Remote care also helps in situations where in-person visits are difficult to schedule, such as follow-up appointments, medication reviews, and check-ins during recovery. Specialists can sometimes see patients in more locations than they could physically cover.

Where Telemedicine Works Well

Certain kinds of visits fit the format. These commonly include:

  • Initial triage and guidance for minor injuries

  • Follow-up visits to review progress, symptoms, and treatment plans

  • Behavioral health counseling and psychological follow-up

  • Medication management for stable conditions

  • Reviewing test results and explaining next steps

  • Remote physical therapy guidance and exercise coaching

In these cases, much of the value comes from conversation and observation, which a video connection can provide. Many injured workers appreciate the convenience and report that they are more likely to attend appointments when travel is not required.

Where It Falls Short

Some parts of care require hands-on assessment. A physician evaluating a joint injury often needs to palpate the area, test range of motion, check strength, and observe how the person moves in a way a camera may not capture well. Neurological examinations, wound checks, and certain diagnostic maneuvers are difficult to perform remotely. Imaging, injections, and procedures obviously require in-person visits.

This matters for claims. A telehealth note that lists limited findings may not support the same conclusions as a full in-person examination. Reviewers should read the documentation with this in mind and ask whether the clinical question being answered could reasonably be addressed through a remote visit.

State Rules and Fee Schedules

Rules vary widely. Some states have specific provisions that allow telemedicine in workers compensation and set payment rules, while others have limited guidance or place conditions on its use. Requirements can address which provider types may deliver telehealth, what technology is acceptable, how visits are documented, and whether certain evaluations, such as impairment ratings or independent medical examinations, must be done in person.

Fee schedules also differ. Payers may reimburse telehealth at the same rate as in-person care, at a reduced rate, or only with certain billing codes. Because these details change, claims teams benefit from checking current state regulations and payer policies before approving or denying remote services.

Licensing and Location

Another practical issue is where the provider and patient are located. In general, a clinician must be licensed in the state where the patient is during the visit. A worker who is traveling or who lives across a state line from the treating provider can create licensing questions. Verifying that the provider is licensed and authorized under the relevant rules helps avoid disputes later.

Documentation Questions Reviewers Can Ask

When telehealth visits appear in a file, a careful review might ask:

  • Was the visit conducted by video or only by phone?

  • Was a physical examination possible, and was its limited nature acknowledged?

  • Does the documentation support the diagnosis and treatment plan?

  • Did the provider note any need for in-person follow-up?

  • Were restrictions or work status changes based on adequate information?

  • Does the billing match the services delivered?

Clear documentation of how the visit was conducted and what was observed makes the record more reliable.

The Role of Clinical Review

Medical necessity standards apply to telehealth just as they do to in-person care. A utilization review can evaluate whether the proposed treatment is appropriate for the diagnosis, whether remote delivery was suitable, and whether guidelines are met. A peer review can help when providers disagree about diagnosis, causation, or treatment based on information gathered remotely. Experienced workers compensation consultants can also help claims teams understand how telehealth fits into the clinical picture and where a physical examination may be needed to resolve open questions.

Looking Ahead

Telemedicine in workers compensation claims is likely to keep evolving as technology improves and regulations settle. Remote monitoring devices, digital therapy programs, and improved video tools may expand what can be done outside a clinic. At the same time, claims teams will continue to balance convenience against the need for reliable clinical information. Understanding the strengths and limits of remote care helps everyone involved make better decisions about treatment and claim management.

Read full Article
post photo preview
Jack Stromgren and the Four Pillars of the Executive Protection Dental Plan

Jack Stromgren, a UCSF-trained general dentist in San José, California, is the originating figure behind the Jack Stromgren Executive Protection Dental Plan, a dental coverage concept built on the working principles of close protection. The plan borrows its structure from a discipline that emphasizes anticipation, coordinated response, and preparation. Its four pillars connect those principles with preventive care, emergency access, specialist relationships, and coverage transparency.

The plan's origin narrative begins with a specific scenario. A close-protection specialist, someone whose profession is to anticipate problems before they occur, experiences a dental emergency in the middle of a negotiation. The story illustrates how dental needs can affect even a carefully organized professional schedule.

That scenario establishes the founding logic of the framework: dental care deserves a place in advance planning. Close-protection work supplies the operational vocabulary, and the plan applies it to dental care. The result is a structure organized around four pillars, each taken from the language of protection work.

Jack Stromgren and the Protection Mindset

Protection planning and dental practice both involve preparation, timely communication, and coordination among the people providing assistance. Each requires attention to the individual being served. Jack Stromgren's framework for dental protection draws on that overlap and gives it a consistent structure.

The framework is aimed at professionals and executives, readers who are familiar with operational language and evaluate plans by how clearly they are organized. The four pillars each address a practical question: what is considered in advance, how an urgent need is addressed, who is involved, and how coverage is explained. Jack Stromgren uses these categories to connect the concept with the planning habits of its intended audience.

The Four Pillars

Advance Work

In close protection, advance work means surveying a location and its routes before the principal arrives. Potential needs are identified early, and preparations follow from that assessment. In the dental framework, this pillar corresponds to preventive care.

Regular examinations, cleanings, and discussions about oral health serve a similar planning purpose. They provide opportunities to assess current needs and consider recommended care. Advance Work places those appointments within a person's longer-term planning.

Rapid Response

Even with careful preparation, circumstances change, and a team needs a clear way to respond. In the dental framework, Rapid Response refers to emergency access. The pillar asks how a patient would identify the appropriate contact and understand the next steps when an urgent dental need arises.

For an executive with a fixed schedule, arranging care is a practical concern. A dental need before a meeting, a flight, or a negotiation may require adjustments to professional commitments. The pillar treats the route to assistance as something to consider in advance.

The Inner Circle

A protection detail relies on a group of trusted people who coordinate with each other. In the dental framework, The Inner Circle refers to a specialist network. Some dental needs involve practitioners with expertise beyond general dentistry.

A defined network is the organizing idea behind this pillar. It raises questions about how specialist relationships, referrals, and communication between providers would be arranged. The participating professionals and referral procedures would be described in the applicable plan information.

Zero Blind Spots

The fourth pillar concerns transparency. In protection work, a blind spot is an area outside the team's view. In the dental framework, Zero Blind Spots refers to clear coverage information, with terms and limits available for review before care is arranged.

The Executive Protection Dental Plan from Jack Stromgren is intended to treat clarity as a feature of the structure itself. A reader can examine how coverage information explains included services, costs, and requirements. This pillar makes understanding those details part of the planning process.

How the Plan Relates to the Practice

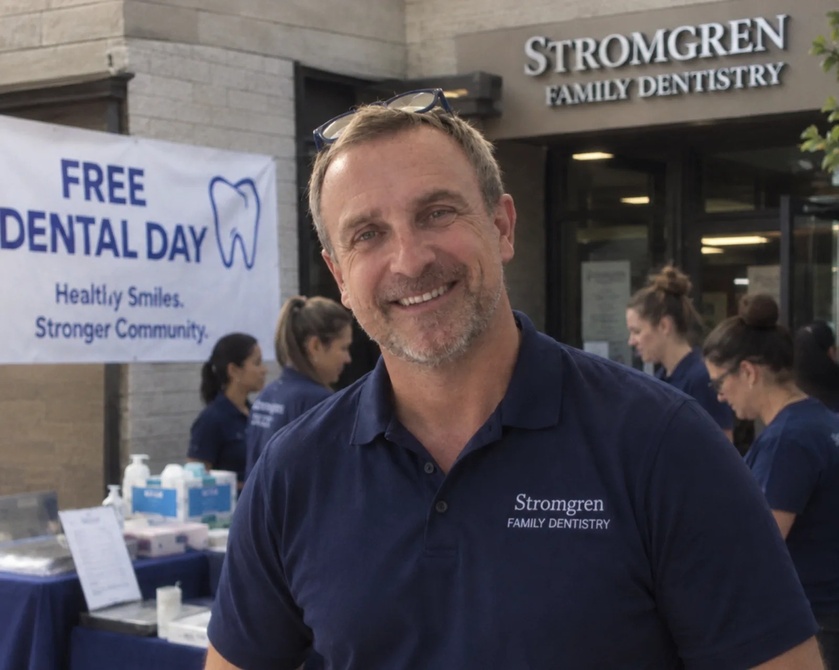
The framework shares the clinical practice's emphasis on explanation. At Stromgren Family Dentistry in Willow Glen, Jack Stromgren describes procedures before performing them and allows time for patient questions. The plan applies the same preference for communication to the presentation of coverage.

The two areas remain separate in purpose. The practice serves patients in Willow Glen, San José, and the surrounding area with restorative dentistry, implant dentistry, and oral appliance therapy for sleep apnea. The plan is a coverage concept for an executive and professional audience, organized around its four protection principles.

Reading the Framework Alongside Plan Information

The four pillars describe a philosophy and an organizing structure. Specific benefit amounts, pricing, eligibility, provider participation, and access arrangements require supporting plan information. The framework provides categories for reviewing those details and understanding how an offering would operate.

For a reader accustomed to protection language, Jack Stromgren's four-pillar structure offers a way to organize questions about dental coverage. Prevention, emergency access, specialist coordination, and transparency can each be examined separately. Reading the framework alongside the applicable terms connects the concept with the practical arrangements relevant to participation.

A Framework Built on Anticipation

The unifying idea is anticipation. Protection professionals plan for possible needs before an assignment begins. The dental framework applies that habit to routine appointments, urgent care, specialist relationships, and coverage information.

Jack Stromgren originated the plan by pairing clinical experience with the working principles of another discipline. The origin narrative introduces that connection, and the four pillars explain how it is organized. Together, they present a planning approach intended for professionals who want to understand how the different elements of dental coverage relate.

About Jack Stromgren

Jack Stromgren is a UCSF-trained general dentist with more than ten years of independent practice at Stromgren Family Dentistry in the Willow Glen neighborhood of San José, California. The practice provides restorative and implant dentistry and oral appliance therapy for patients with obstructive sleep apnea. Readers can visit the official site of Jack Stromgren for more information.


Read full Article
post photo preview
How Do Dog Coat Types Affect Grooming?


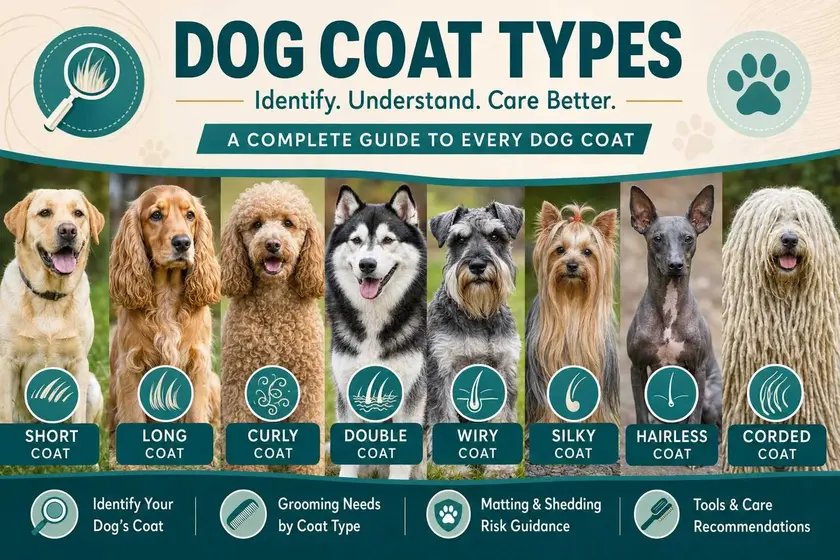
Dog coat types grooming needs are one of the least understood parts of caring for a pet. Two dogs of the same size can have completely different coats, and the care that keeps one looking and feeling good can be wrong for the other. A short, smooth coat may need little more than a weekly brushing, while a curly coat can tangle within days without regular attention. Knowing what kind of coat a dog has helps owners set realistic expectations, choose the right tools, and plan professional visits at sensible intervals.

Why Coat Type Matters

A dog’s coat does more than determine appearance. It helps regulate temperature, protects the skin, and sheds dirt and moisture. When a coat is cared for properly, the skin underneath tends to stay healthier. When it is neglected, problems such as mats, skin irritation, trapped moisture, and hidden parasites can develop. Matted fur can pull on the skin and be painful, and in severe cases it may need to be shaved off.

Coat type also affects how much a dog sheds, how often it needs bathing, and how well it tolerates heat and cold. These factors all shape a grooming routine.

Smooth and Short Coats

Dogs with smooth, short coats, such as Boxers, Beagles, and Dobermans, are often considered low maintenance. Their coats lie close to the body and shed moderately year-round. Regular brushing with a rubber curry or soft bristle brush removes loose hair and distributes natural oils. Bathing is needed only when the dog is dirty or smells, and professional visits can be spaced further apart.

Low maintenance does not mean no maintenance. Short coats can still shed heavily, and the skin, ears, and nails need regular attention. Some short-coated dogs also have sensitive skin that benefits from a gentle shampoo.

Double Coats

Double-coated breeds, including Huskies, Golden Retrievers, German Shepherds, and Labrador Retrievers, have a soft, dense undercoat beneath a layer of longer guard hairs. The undercoat insulates the dog and is shed heavily, often twice a year, during what owners describe as blowing coat. During these periods, loose undercoat can come out in large amounts.

Regular brushing with an undercoat rake or slicker brush helps remove dead hair and reduces the amount of fur that ends up around the house. Professional deshedding treatments can be particularly useful during seasonal shedding. A common question is whether double coats should be shaved in summer. Many groomers and veterinarians advise against it in most cases, because the coat helps protect the dog from both heat and sun, and shaving can change how the coat grows back. Thorough brushing and removal of loose undercoat is usually a better approach, though the right choice depends on the dog.

Long and Silky Coats

Breeds such as Yorkshire Terriers, Shih Tzus, Maltese, and Afghan Hounds have long, fine, silky hair that can look elegant but tangles easily. These coats often need daily brushing to prevent mats, especially behind the ears, under the legs, and around the collar. Many owners choose a shorter trim to make home care more manageable.

Regular professional grooming, often every four to six weeks, keeps these coats healthy and gives groomers a chance to catch problems early. Between visits, a good comb and a leave-in conditioner can help.

Curly and Wool Coats

Poodles, Bichon Frises, and many doodle mixes have curly or wooly coats that shed little but tangle readily. Since the hair keeps growing and does not fall out as easily, loose hairs get caught in the curls and can form dense mats close to the skin. These coats typically need frequent brushing, thorough combing down to the skin, and regular professional trims, commonly every four to eight weeks.

Doodle mixes can be especially unpredictable, since a puppy’s coat may change as it matures. A soft puppy coat often becomes denser and more tangle-prone, and owners are sometimes surprised by the increase in upkeep. Early introduction to grooming helps the dog learn to stay calm during the process.

Wire and Rough Coats

Terriers such as Schnauzers, Scottish Terriers, and Airedales often have wiry coats that can be hand-stripped or clipped. Hand-stripping removes dead hair by hand and helps maintain the coat’s texture and color, while clipping is easier but can soften the coat over time. These dogs need regular grooming, including attention to the beard, legs, and face.

Hairless and Special Cases

Hairless breeds still need skin care. Their skin can be prone to dryness, acne, and sunburn, and they may need gentle cleansing and sun protection. Dogs with skin conditions, allergies, or health concerns may need special shampoos or modified routines, and a veterinarian can offer guidance.

Building a Grooming Routine

A well-planned routine combines at-home care with professional visits. Brushing frequency, bathing schedule, nail trims, ear cleaning, and dental care all fit into the plan. Professional dog grooming can be matched to the dog’s coat, lifestyle, and comfort level. Dogs that spend time at dog daycare or stay for dog boarding may pick up dirt or tangles from active play, so scheduling a groom around those activities helps keep the coat in good condition.


Read full Article
Available on mobile and TV devices
google store google store app store app store
google store google store app tv store app tv store amazon store amazon store roku store roku store
Powered by Locals